 TacticScale
What Zebra Technologies Does & How It Makes Money (ZBRA)
Updated October 2026 · reflects Zebra Technologies's latest reported financials
Maker of barcode scanners, label printers, and rugged mobile computers. Zebra earns most of its revenue from selling hardware like printers, scanners, and mobile computers through its direct sales force and channel partners.
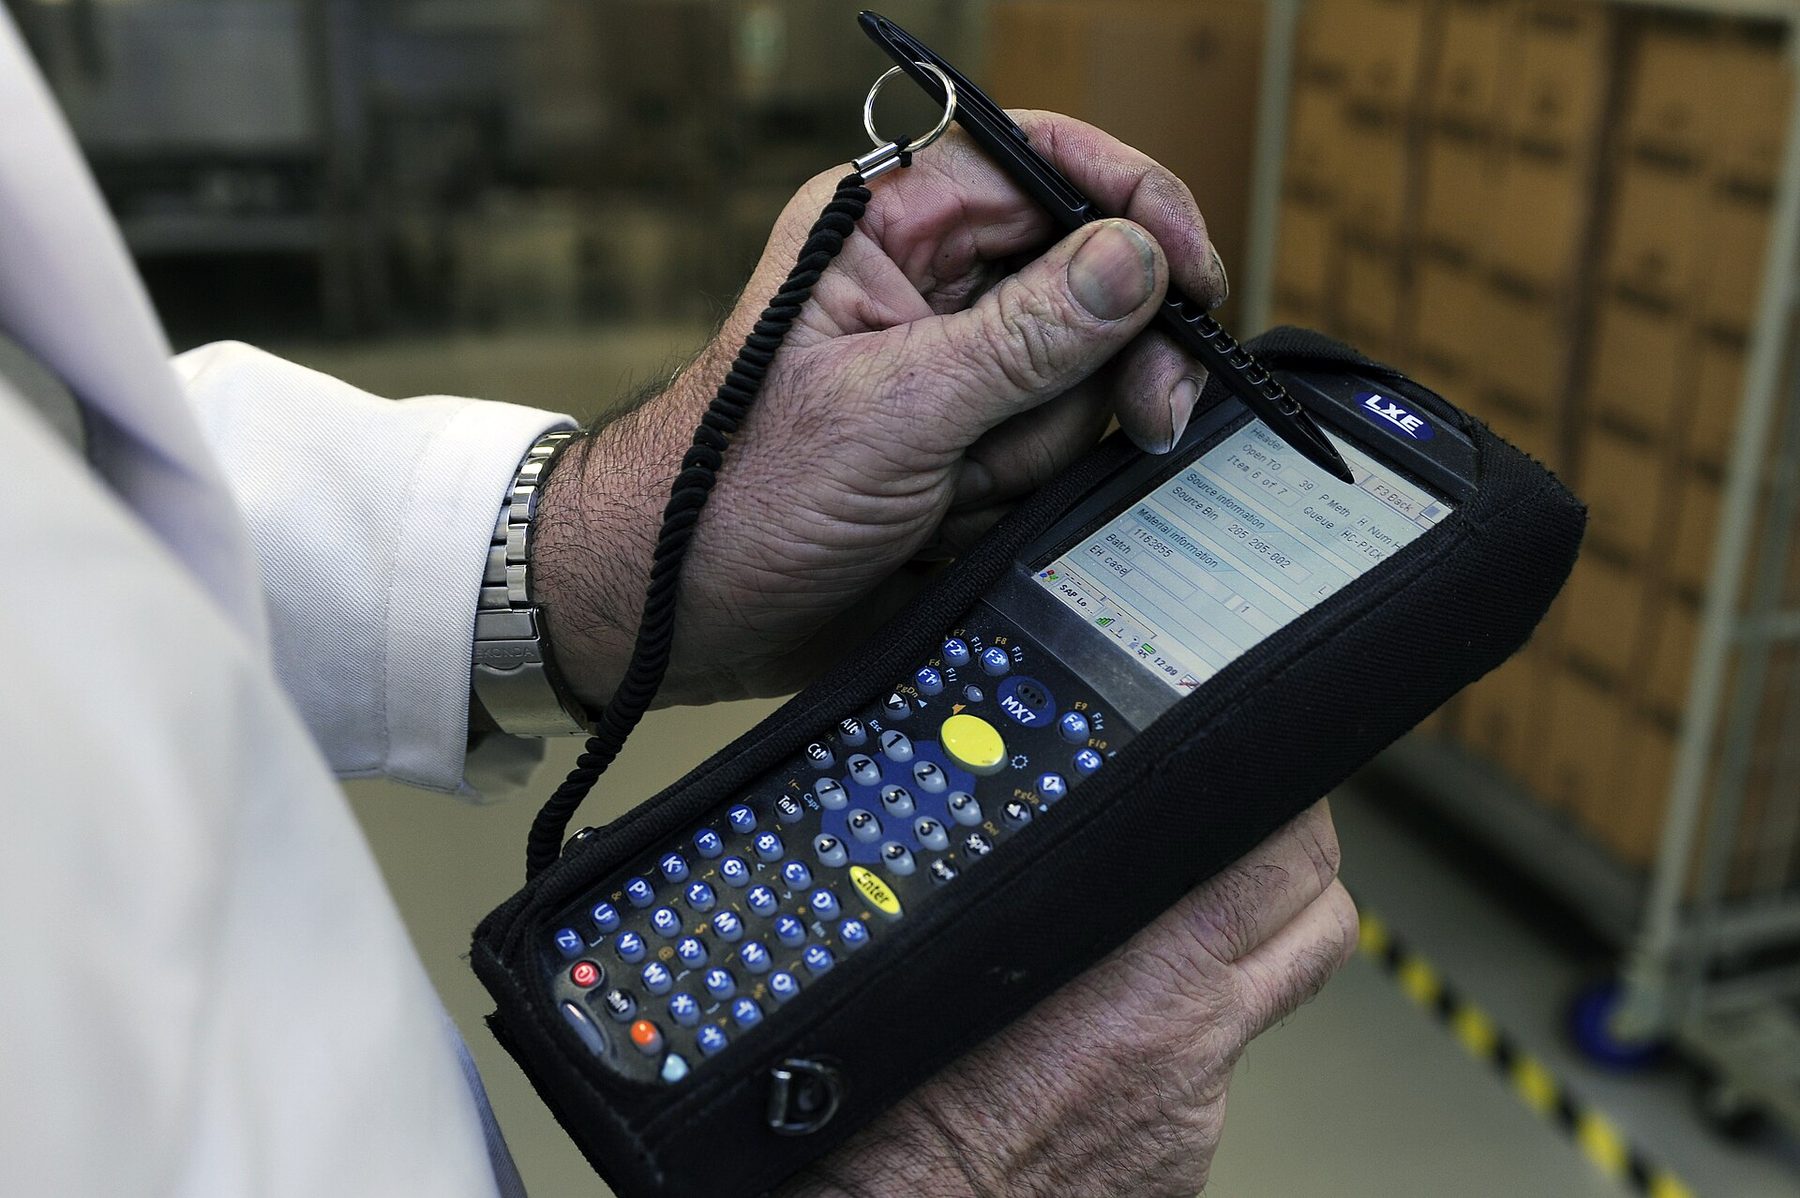
How Zebra Technologies makes money
Zebra earns most of its revenue from selling hardware like printers, scanners, and mobile computers through its direct sales force and channel partners. It adds recurring revenue from consumables such as labels, ribbons, and RFID tags, plus maintenance, repair, software, and managed services.
What Zebra Technologies does
Zebra Technologies, founded in 1969 and based in Lincolnshire, Illinois, works in automatic identification and data capture. It reports two segments. Connected Frontline covers mobile computing and workflow software, and Asset Visibility and Automation covers printing, RFID, scanning, and machine vision. Its lineup includes thermal label, receipt, wristband, and card printers, RFID printers and readers, barcode scanners, rugged mobile computers, real-time location systems, machine vision cameras, and self-serve kiosks. Beyond hardware, Zebra sells consumables such as labels, ribbons, and RFID tags. It also offers maintenance, repair, and managed services, along with cloud-based software for workforce management, task execution, and analytics. Its customers are in retail and e-commerce, manufacturing, transportation and logistics, healthcare, and the public sector, and it reaches them through a direct sales force and a network of channel partners.
Products & services
- Barcode and RFID label printers
- Rugged enterprise mobile computers
- Barcode scanners and imagers
- RFID readers, tags and sleds
- Industrial machine vision cameras
- Workforce management and workflow software
What is Zebra Technologies worth?
On an owner-earnings DCF, Zebra Technologies's most-likely value is about $422 versus a recent price near $387 (9% below fair value). But TacticScale only calls a stock undervalued when the price sits below its conservative no-growth floor (~$211) with a margin of safety — so the honest verdict here is “Fairly priced — no edge.” Fair value earns its keep only at the extremes, not in the wide middle.
Price sits in the normal range — fair value isn't actionable here; it earns its keep only when price drops below the no-growth floor, or runs to roughly double the optimistic case.
Analysis, not advice. Fair value is a margin-of-safety estimate from a deterministic owner-earnings DCF, not a price target or recommendation. See the full breakdown →
Related companies
ZTE (000063.SZ) · ScanSource (SCSC) · BlackBerry (BB) · GE HealthCare Technologies (GEHC)