 TacticScale
What Baker Hughes Does & How It Makes Money (BKR)
Updated October 2026 · reflects Baker Hughes's latest reported financials
Energy technology company supplying oilfield services and industrial gas equipment. It earns revenue by selling oilfield equipment and providing drilling, completion and production services to oil companies.
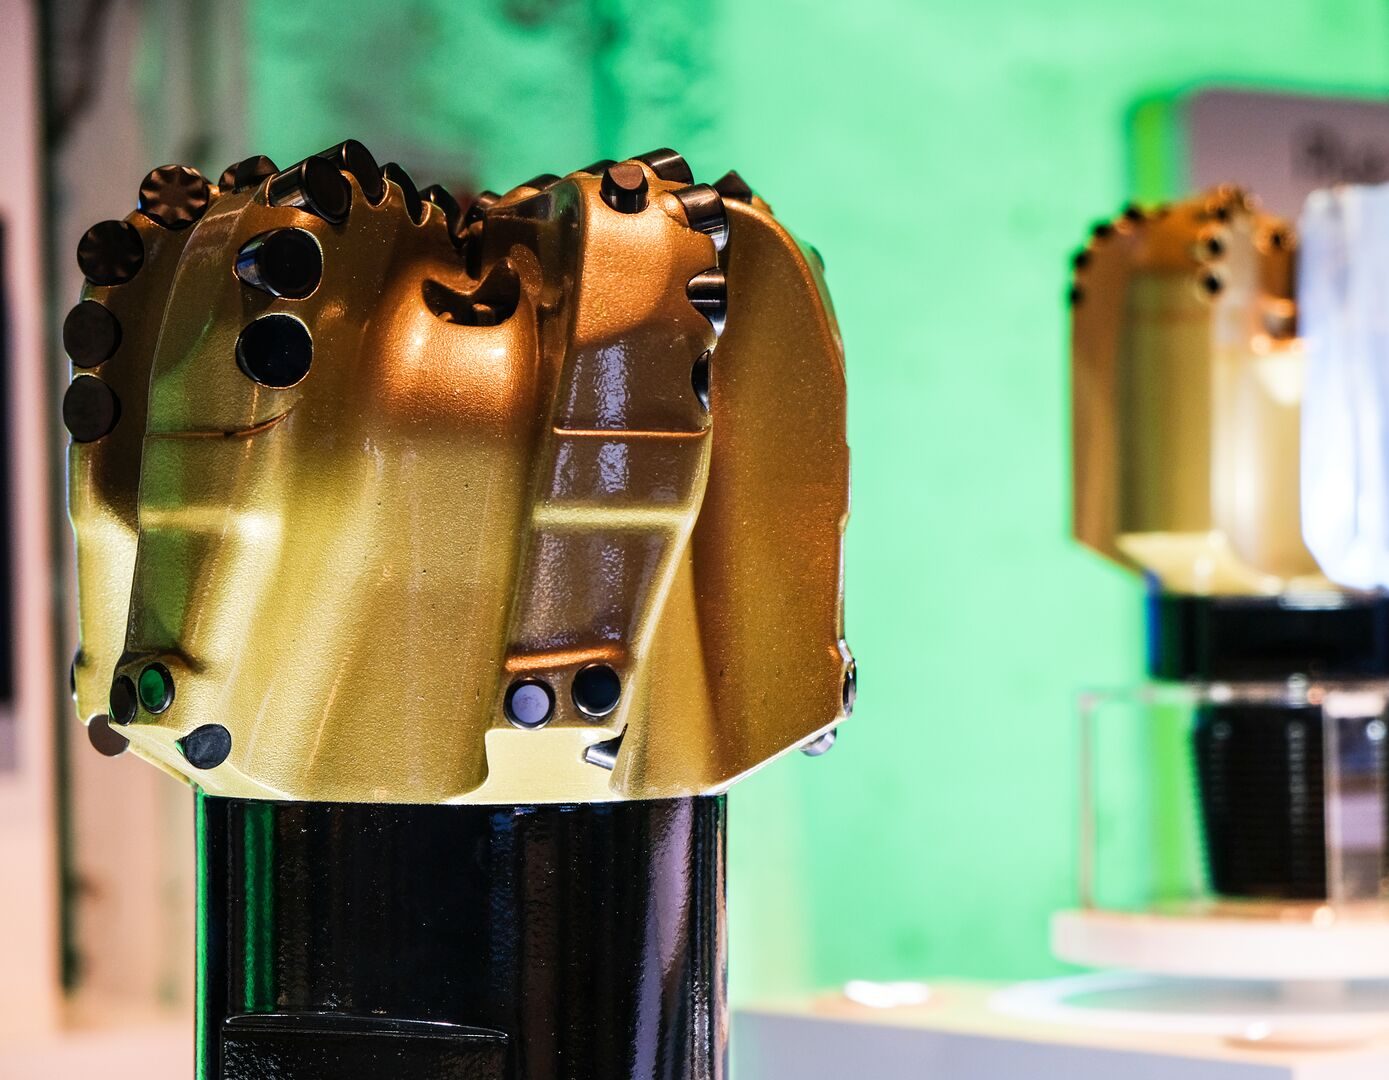
How Baker Hughes makes money
It earns revenue by selling oilfield equipment and providing drilling, completion and production services to oil companies. It also sells gas technology equipment and makes ongoing money from aftermarket support, maintenance, sensing hardware and software for industrial and energy customers.
What Baker Hughes does
Baker Hughes is a Houston-based energy technology company operating through two segments. Oilfield Services & Equipment covers the full life of an oil or gas well, from exploration and drilling to production and decommissioning. Its offerings include drill bits and fluids, completions, wireline and pressure pumping services, artificial lift, oilfield chemicals, subsea projects, flexible pipe and surface pressure control. Customers include independent, international and national oil companies, EPC contractors and geothermal operators. Industrial & Energy Technology supplies gas technology equipment, including drivers, compressors and turnkey power-generation solutions, along with aftermarket and uptime services. It also offers non-destructive testing, flow control, gear transmission systems, Bently Nevada monitoring hardware, Cordant optimization software and climate technology solutions. Formerly Baker Hughes, a GE company, it adopted its current name in October 2019.
Products & services
- Drilling services, drill bits and fluids
- Completions, wireline and pressure pumping services
- Subsea systems and flexible pipe
- Gas technology equipment (compression and power generation)
- Bently Nevada vibration monitoring sensors
- Cordant asset optimization software
What is Baker Hughes worth?
On an owner-earnings DCF, Baker Hughes's most-likely value is about $45 versus a recent price near $57 (21% above fair value). But TacticScale only calls a stock undervalued when the price sits below its conservative no-growth floor (~$25) with a margin of safety — so the honest verdict here is “Fairly priced — no edge.” Fair value earns its keep only at the extremes, not in the wide middle.
Price sits in the normal range — fair value isn't actionable here; it earns its keep only when price drops below the no-growth floor, or runs to roughly double the optimistic case.
Analysis, not advice. Fair value is a margin-of-safety estimate from a deterministic owner-earnings DCF, not a price target or recommendation. See the full breakdown →
Related companies
Halliburton (HAL) · SLB (SLB) · Weatherford International (WFRD) · Yantai Jereh Oilfield Services (002353.SZ)