 TacticScale
What Wynn Resorts Does & How It Makes Money (WYNN)
Updated October 2026 · reflects Wynn Resorts's latest reported financials
Operator of luxury integrated casino resorts in Macau, Las Vegas, and Boston. It earns money mainly from casino gaming (table games, slots, private VIP salons, and sports betting), plus hotel rooms, food and beverage, retail space, meetings and conventions, and entertainment at its resorts.
How Wynn Resorts makes money
It earns money mainly from casino gaming (table games, slots, private VIP salons, and sports betting), plus hotel rooms, food and beverage, retail space, meetings and conventions, and entertainment at its resorts.
What Wynn Resorts does
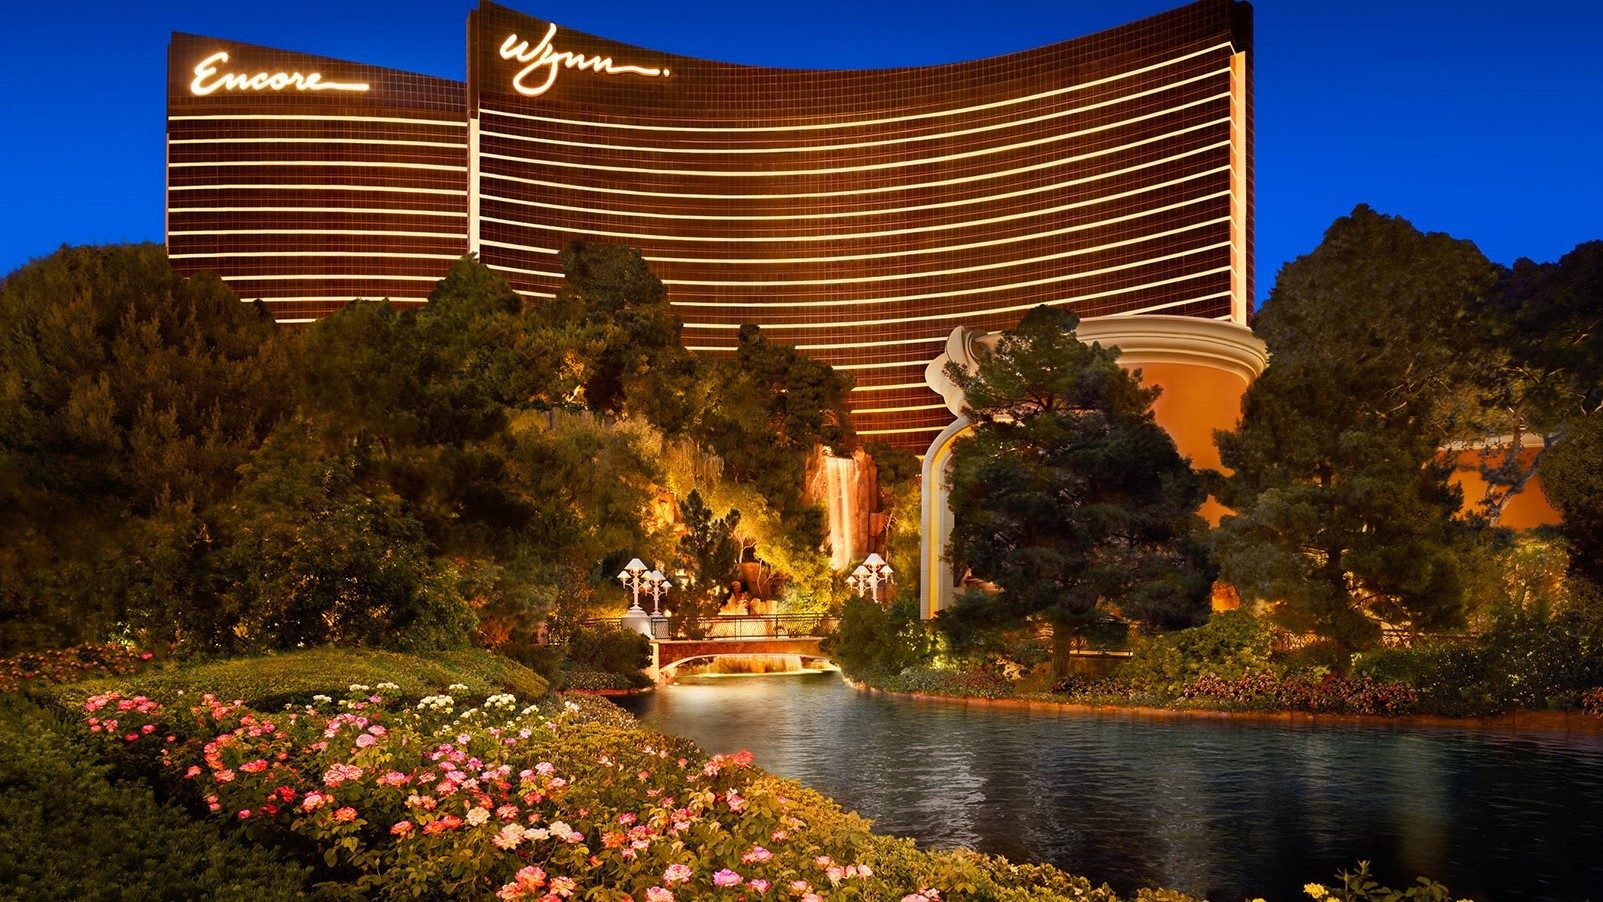
Wynn Resorts, Limited designs, develops, and operates luxury integrated resorts, reporting four segments: Wynn Palace, Wynn Macau, Las Vegas Operations, and Encore Boston Harbor. Each property combines casino floors, private gaming salons, and high-limit areas with luxury hotel towers, spas, restaurants, retail, and meeting and convention space. The properties also rely heavily on entertainment and attractions. These include performance lakes and a gondola ride in Macau, nightclubs, a beach club, theaters, and a golf course in Las Vegas, and a waterfront park and water shuttles at Encore Boston Harbor. The company was incorporated in 2002 and is headquartered in Las Vegas, Nevada.
Products & services
- Wynn Palace (Macau)
- Wynn Macau
- Wynn Las Vegas resort operations
- Encore Boston Harbor
- Private gaming salons and sky casinos
- Luxury hotel suites and villas
What is Wynn Resorts worth?
On an owner-earnings DCF, Wynn Resorts's most-likely value is about $90 versus a recent price near $75 (20% below fair value). But TacticScale only calls a stock undervalued when the price sits below its conservative no-growth floor (~$56) with a margin of safety — so the honest verdict here is “Fairly priced — no edge.” Fair value earns its keep only at the extremes, not in the wide middle.
Price sits in the normal range — fair value isn't actionable here; it earns its keep only when price drops below the no-growth floor, or runs to roughly double the optimistic case.
⚠ High leverage — net debt is 9.5× annual cash flow. Net debt is subtracted from this fair value, but refinancing at higher rates, principal timing, and share dilution aren’t modeled — the equity can be worth far less if cash flow weakens.
Analysis, not advice. Fair value is a margin-of-safety estimate from a deterministic owner-earnings DCF, not a price target or recommendation. See the full breakdown →